Ministry of Finance Push Aims to Bring New Financial Competitors to Israel
The Ministry of Finance expects new local and international financial competitors, including Revolut, to enter Israel's banking sector, potentially saving the public 1.5 billion shekels annually in interest.
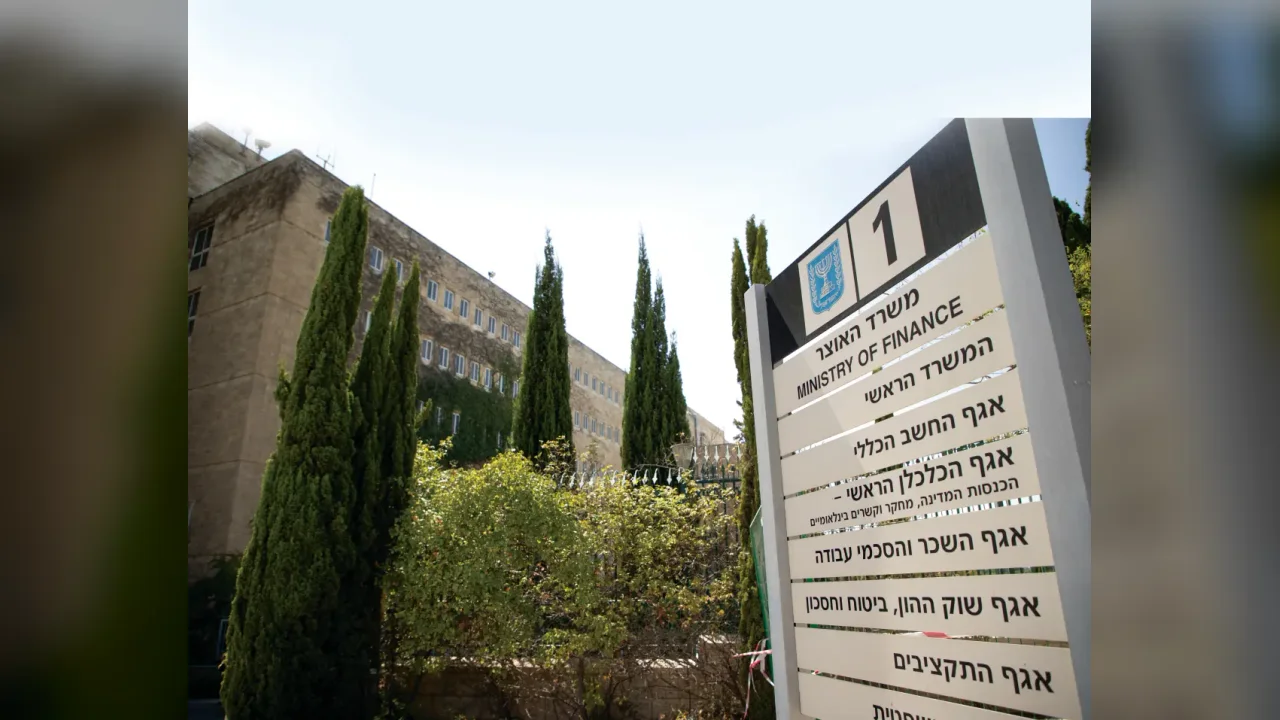
The entry of British fintech giant Revolut into the Israeli market marks only the initial phase of a broader banking sector overhaul planned by the Ministry of Finance, as additional domestic and international financial institutions hold discussions regarding potential local operations. Ministry officials estimate that heightened market competition could save the public at least 1.5 billion shekels annually in interest expenses alone.
At the core of the planned reform lies a straightforward objective: enabling citizens to earn higher returns on their savings while paying lower rates on loans. Currently, hundreds of billions of shekels belonging to Israeli households sit in non-interest-bearing current accounts or low-yield deposits. For traditional lenders, these funds serve as an inexpensive financing source, while customers fail to capture the full market yield on their capital.
Expanding Competition and Lowering Costs
The arrival of new banking entities aims to reshape this dynamic by compelling market entrants to attract customers through lucrative offers, including enhanced deposit rates, improved current account terms, and more affordable credit. Consequently, legacy lenders will likely be forced to upgrade their customer terms to curb client attrition. A key metric underpinning the initiative involves funding cost differentials, as Ministry data indicates that non-bank credit providers faced funding sources roughly 2% more expensive than banks in 2024, granting traditional institutions a substantial pricing advantage on loans.
When a non-bank financial entity secures a banking license and gains the ability to mobilize public deposits, its funding costs decline, enabling more competitive credit offerings. Beyond household banking, the reform is projected to benefit small and medium-sized enterprises, such as retail shops, cafes, and importers, which currently shoulder heavy credit burdens. Cheaper loans and streamlined currency exchange services can lower operating expenses, boost profit margins, and facilitate more competitive consumer pricing.
Institutional Participation and Digital Standards
Another pillar of the reform opens the door for institutional investors to establish banks, subject to strict regulatory safeguards preventing conflicts of interest. These institutional players bring substantial capital, extensive money management expertise, and established client bases. In parallel, the entry of international technology firms like Revolut is expected to elevate service quality standards through fully digital account opening, rapid cross-border transfers, and advanced currency conversion tools.
Ultimately, the ultimate test of the reform rests on translating new market entrants into tangible savings for the public, with the projected 1.5 billion shekels in annual savings contingent upon Israel converging toward international levels of market competition. If competition successfully expands, beneficiaries will encompass not only clients migrating to new institutions, but millions of Israeli consumers remaining with legacy lenders who secure upgraded financial terms.