Real Estate Slowdown Pressures Israeli Developers Ahead of 2027
Israel's real estate slowdown challenges developers ahead of 2027, forcing credit institutions to prioritize cash flow over asset valuation as sales lag behind original projections.
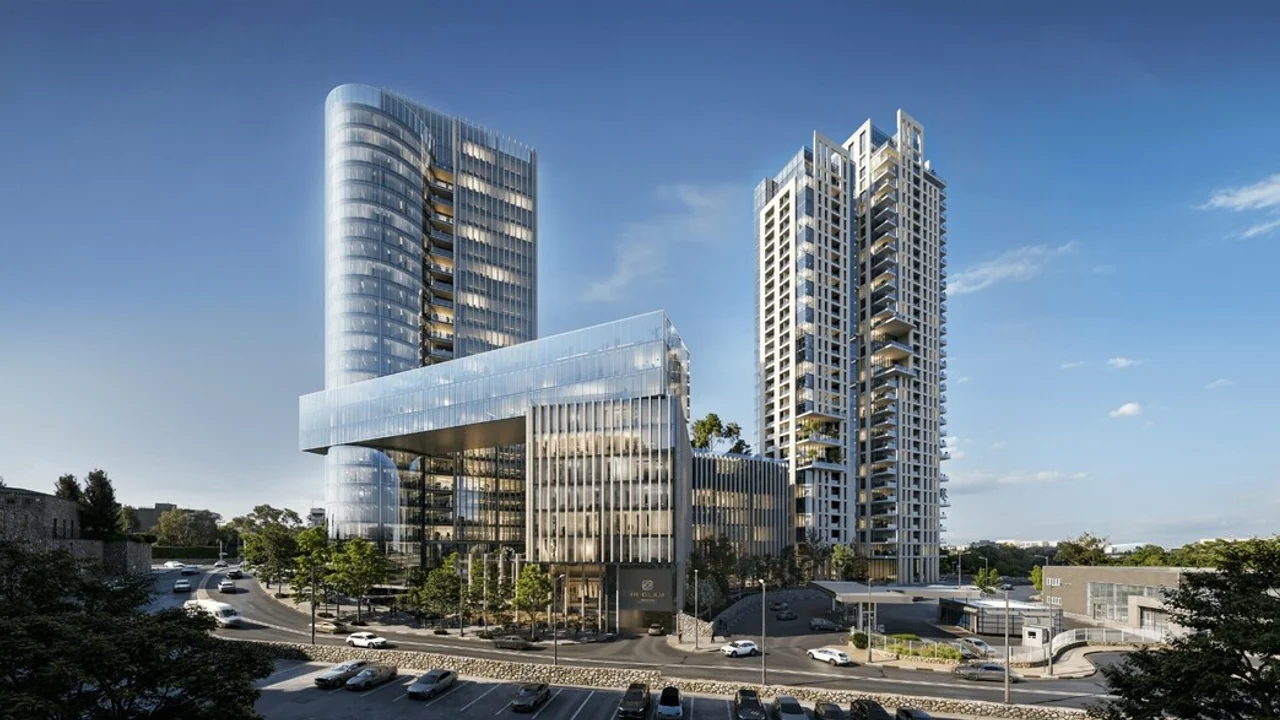
The slowdown in apartment sales across Israel's real estate market is presenting developers with a mounting challenge as 2027 approaches: meeting financing obligations amid lower-than-expected sales. While industry discourse largely focuses on housing prices and transaction volumes, credit institutions are reassessing project financing risks, emphasizing developers' cash flow capabilities to repay debts on time.
An unsold apartment is more than just inventory waiting for a buyer; it represents trapped capital while interest accumulates, maturity dates loom, and the ability to release funds for new projects diminishes. Real estate financing deals rely on assumptions regarding sales pace, construction costs, completion timelines, and projected cash flows. However, shifting interest rates, rising construction costs, and slowing sales have disrupted the foundational assumptions of recent years.
According to Adv. Itai Ram, managing partner at the BGR law firm specializing in non-bank financing and credit representation, cash flow pressure does not necessarily indicate a project's fundamental economic failure. Even a well-located project with quality collateral and strong economic potential can face difficulties when revenues are delayed while obligations persist. In such cases, the core issue is not necessarily asset valuation, but the gap between realization timelines and debt repayment dates.
Valuing Debt Repayment Over Asset Worth
This reality is reshaping how financing institutions evaluate new transactions and manage exposure to existing projects. Alongside land value and loan-to-value ratios, lenders are scrutinizing actual sales rates, developer equity, remaining completion costs, and resilience against missed forecasts.
Ram notes that quality collateral does not automatically guarantee timely repayment. While realizing collateral is a vital safeguard, it should not serve as the primary business scenario for credit extension. Lenders prefer repayments derived from normal project operations rather than lengthy, costly enforcement proceedings. Consequently, the central question is whether a transaction can generate the necessary cash flow for debt service.
Amid shifting market conditions, non-bank financial institutions play a critical role in providing credit solutions to developers, including established real estate firms. Turning to these lenders often stems from the need to tailor credit structures to evolving project requirements rather than outright bank rejections.
Potential solutions include mezzanine financing, inventory-backed loans, restructuring repayment schedules to match projected cash flows, and combining diverse credit sources. Nevertheless, the flexibility offered by non-bank lenders does not eliminate the necessity for rigorous risk assessment.
Widening Gaps Among Real Estate Developers
One potential consequence of the current financing climate is the widening divide between financially robust real estate firms with strong capital access and developers reliant on rapid sales and debt rolling to sustain operations. While liquid firms can endure prolonged slumps and hold inventory until market conditions improve, developers facing near-term liabilities may require complex interventions.
Ram predicts that a defining market trend will be the deepening divergence between financially resilient developers and those dependent on continuous high sales volumes. Developers struggling to meet obligations may face asset sales, equity partnerships, or refinancing under more demanding conditions.
Conversely, this environment may present opportunities for financiers and investors capable of identifying high-potential projects experiencing temporary liquidity constraints. For developers, effective debt management, liquidity preservation, and agile financing structures will prove just as critical as project quality and sales velocity heading toward 2027.