High Financing Costs Threaten Small Real Estate Developers, Analyst Warns
High financing costs and unsold inventory in Tel Aviv and central regions will likely force small real estate developers into mergers, according to Psagot Sigma analyst Avi Shakuri.
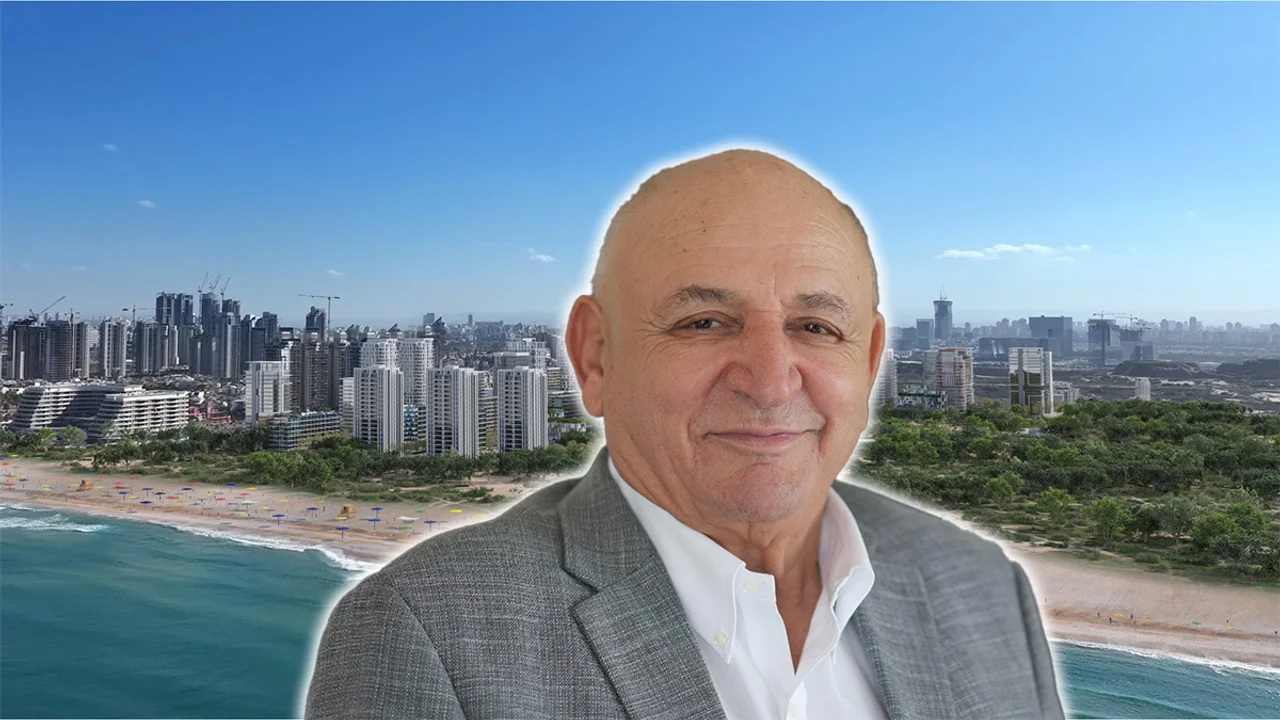
High housing prices and elevated financing costs are expected to burden small developers and increase the need for strategic partners and mergers, according to Avi Shakuri, a senior analyst at Psagot Sigma Capital Markets. He notes that cash-rich companies will be able to leverage this period for low-cost acquisitions.
Challenges for Small Developers
"There is no doubt that small developers will struggle to survive this prolonged period of high interest rates and pressure on selling prices," Shakuri says. Companies that entered this period with low equity relative to their balance sheets will need to strengthen their capital. "Mergers are on the agenda during this period more than ever, and companies with cash will take advantage of this time to buy cheaply."
Shakuri emphasizes that the pressure affects various players, both luxury developers and those building in the periphery. However, he points out that housing inventory in central regions will continue to weigh on the market. Over 55% of unsold apartment inventory is concentrated in the Central District and Tel Aviv. "Large supply creates pressure, and it will continue until sales pick up," he explains.
"There is no doubt that small developers will struggle to survive this prolonged period of high interest rates and pressure on selling prices."
Inventory and Financing Pressures
Based on Ministry of Finance and Central Bureau of Statistics data for August, the national inventory of new unsold apartments stood at approximately 85,680 units. Shakuri estimates that this inventory will continue to pressure sales conditions in the center for over a year. Meanwhile, weakness among trade-up buyers will weigh on demand for large apartments in the central region for six to twelve months. Conversely, demand remains supported by first-time homebuyers and subsidized programs, particularly in the periphery.
Regarding prices, Shakuri notes that declines are already visible in CBS data, while financing benefits and payment spreads further reduce economic costs for buyers. He cites Tidhar CEO Uri Levin's assessment of an approximate 20% decline in prices over the past four years when factoring in financing promotions.
Outlook for Market Recovery
Shakuri assesses that an earlier recovery primarily requires a reduction in concerns over security and political escalation. "People do not know how to plan for next month, let alone commit to a 30-year mortgage," he states. Political certainty, interest rate cuts, and a shift in media sentiment regarding contractors and price trends could ultimately ease the return of buyers to the market.