Israel Prepares 15% Minimum Corporate Tax to Align With Global OECD Rules
Israel is advancing a 15% minimum corporate tax on multinational tech giants with revenues exceeding 750 million euros to align with OECD Pillar 2 rules and prevent foreign tax capture.
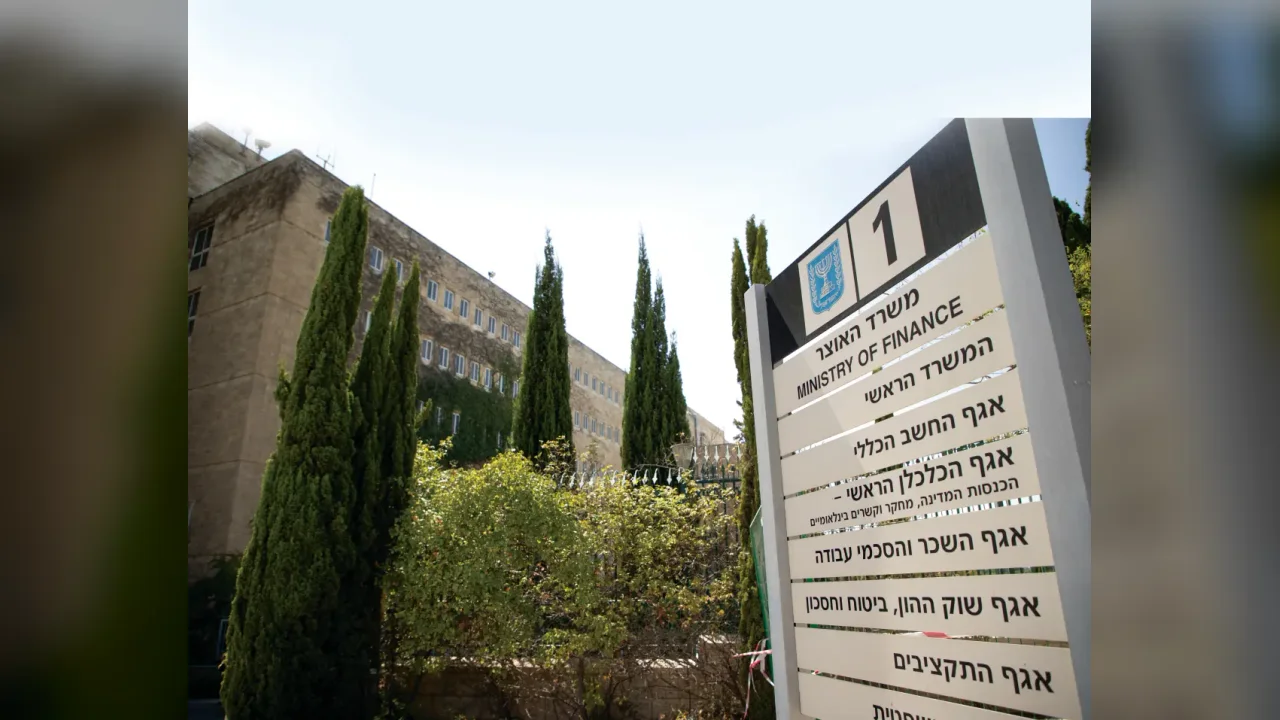
The Ministry of Finance is accelerating the implementation of a global tax reform that will introduce a mandatory 15% minimum corporate tax on multinational enterprises operating in Israel. The Knesset Finance Committee is scheduled to convene on Tuesday to review and approve the supplementary regulations required to enact the Organisation for Economic Co-operation and Development Pillar 2 framework.
The sweeping reform establishes an effective minimum tax rate of 15% on large multinational groups with an annual consolidated revenue of at least 750 million euros. Consequently, multinational tech firms that currently benefit from reduced corporate tax rates in Israel may be required to pay an additional supplementary tax if their effective domestic tax rate falls below the 15% threshold.
Protecting Domestic Tax Revenues
Ministry officials are pushing for urgent approval of the regulations to prevent foreign jurisdictions from capturing tax revenues generated within Israel. Without formal regulatory alignment, parent companies based abroad could be subjected by their home countries to top-up taxes on profits earned locally, causing Israel to forfeit valuable tax proceeds without yielding any actual tax savings for the corporations.
This legislative shift carries profound implications for the Israeli economy and the high-tech sector in particular. International technology giants operate extensive research and development centers across the country, employing thousands of professionals and investing heavily in local operations. Many of these entities have traditionally relied on tax incentives provided under the Law for the Encouragement of Capital Investments, which offers reduced tax rates as low as 6% to attract foreign capital and stimulate industrial innovation.
Calculation Complexities and Future Outlook
While the mandate establishes a 15% floor, the effective tax rate calculation is not uniform. The framework incorporates international guidelines, transition rules, and relief mechanisms that account for a company's substantive economic activities, payroll expenses, and tangible asset holdings.
With primary legislation already approved by the Knesset, the upcoming committee review will finalize the calculation methodology, reporting mandates, and transition protocols slated to take effect for tax years beginning in 2026. As traditional tax incentives narrow, policymakers face the dual challenge of securing domestic revenues while preserving Israel's competitive edge in attracting global technology investments through skilled labor, infrastructure, and regulatory certainty.